Moving abroad after 70 is becoming more common among Americans who want to spend their retirement years overseas. But healthcare planning becomes more important with age, especially if you take regular medication, have an existing medical condition, or expect to spend part of the year in the United States.
Finding international health insurance after age 70 can require more research than buying coverage at a younger age. Some insurers have maximum entry ages, while others offer plans specifically designed for older expatriates. The benefits, exclusions, medical underwriting requirements, and renewal terms can also vary considerably.
If you are over 70 and considering life abroad, here is what you should know before choosing a policy.
Can Seniors Over 70 Get International Health Insurance?
Yes, some international health insurance providers offer coverage to people over 70. However, there is no single age limit that applies to every international health insurance company.
Some insurers set maximum entry ages, while others have products designed specifically for retirees and older expatriates. For example, AXA Global Healthcare states that it accepts retired expatriates under age 80 on its retiree health insurance product, with different conditions applying to applicants over 80.
Other international insurers have lower entry limits. This is why someone turning 70 should not assume that every available plan will accept a new application.
Your age at the time you apply matters, so it is worth researching coverage before you move abroad.
Why Is Insurance More Difficult After 70?
Age is one factor insurers consider when assessing international medical insurance applications. Medical history can also become more important.
An insurer may ask about previous diagnoses, surgeries, medications, treatments, or other medical conditions. Depending on the policy, medical underwriting can result in standard coverage, exclusions, additional terms, or a decision not to offer coverage.
The rules are different from one provider to another.
For this reason, comparing several international health insurance options can be particularly important for applicants over 70.
What Does Medicare Cover Overseas?
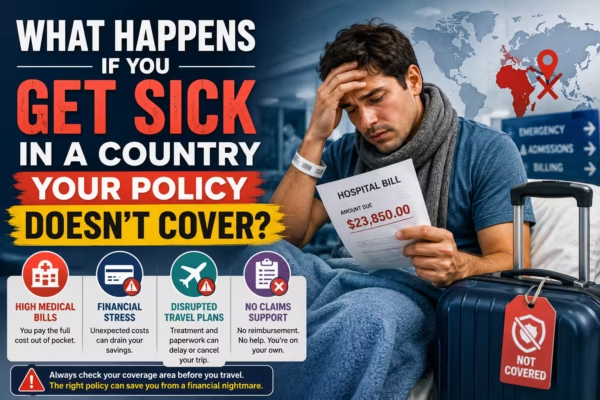
If you are an American over 70, you may already have Medicare. However, Medicare generally provides very limited coverage outside the United States.
Medicare states that in most situations it does not pay for healthcare or supplies received outside the U.S. There are limited exceptions, including certain situations involving emergency treatment when specific conditions are met.
That means Medicare should not automatically be treated as your primary health insurance while living overseas.
Medicare itself notes that people traveling outside the United States may consider travel insurance for additional protection, although travel insurance is not necessarily the same as comprehensive health insurance.
If you plan to live abroad rather than simply take a short vacation, you may need to look at international medical insurance separately.
Should You Keep Medicare After Moving Abroad?
This is an individual decision, and it can have long-term consequences.
Some Americans living overseas keep Medicare because they expect to return to the United States for medical treatment. Medicare specifically notes that people living outside the U.S. may want Part B if they plan to return to the United States for healthcare.
Dropping Medicare Part B can also have consequences. Medicare explains that people who drop Part B may face a late enrollment penalty if they later reenroll without qualifying for a Special Enrollment Period.
Before making a decision about Medicare, consider discussing your situation with Medicare or a qualified Medicare professional. International health insurance and Medicare serve different purposes and should not be assumed to be interchangeable.
What Should Seniors Look For in an International Health Plan?
For someone over 70, the details of the policy can matter more than the headline premium.
When comparing plans, look at:
- Maximum entry age
- Renewal rules
- Geographic area of coverage
- Whether the United States is included
- Inpatient treatment
- Outpatient treatment
- Specialist consultations
- Prescription medication benefits
- Emergency treatment
- Medical evacuation
- Deductibles
- Annual benefit limits
- Pre-existing condition provisions
- Waiting periods
- Exclusions
Not every plan includes all of these benefits, and some may be optional.
The important thing is to compare policies based on the healthcare you are actually likely to use.
Pre-Existing Conditions After 70
Pre-existing conditions are one of the biggest issues for older applicants.
A pre-existing condition may include a medical condition you had before applying for insurance. However, the exact definition and treatment of that condition depends on the policy.
An insurer may cover a condition, exclude it, apply special terms, or decline an application depending on its underwriting rules.
Do not assume that an insurer will treat your medical history the same way another company does.
If you have diabetes, heart disease, cancer history, high blood pressure, or another ongoing condition, provide accurate information during the application process. Leaving out medical information can create problems later if you need to make a claim.
Should You Include U.S. Coverage?
Americans over 70 should think carefully about whether they need healthcare coverage in the United States.
If you plan to spend most of the year overseas and only make occasional visits to America, a plan without U.S. coverage may be worth considering.
On the other hand, if you expect to spend several months each year in the U.S. or want the option of receiving planned treatment there, worldwide coverage that includes the United States may be important.
U.S. coverage can affect the cost of an international health insurance policy, so compare plans based on your actual travel pattern.
How Much Does International Health Insurance Cost After 70?
There is no standard premium for someone over 70.
The price can depend on age, country of residence, medical history, geographic coverage, deductible, benefit level, and whether the United States is included.
International insurance providers publish different pricing structures. Current 2026 information from insurers and international insurance specialists shows that premiums can vary substantially based on age, location, and selected benefits.
Be cautious about articles promising a specific annual price for everyone over 70. A quote based on one person’s circumstances may be very different from the price available to another applicant.
The best way to determine your actual cost is to obtain quotes based on your age, destination, and coverage requirements.
What If You Are Already Living Abroad?
You do not necessarily have to be living in the United States when applying for international health insurance.
However, whether you can apply while already overseas depends on the insurer, plan, country of residence, and age requirements.
Some international products specifically allow applications from people who are already abroad, while others have restrictions. If you have already moved, don’t assume that you have no options. Ask which plans are available to residents of your current country.
How to Compare Plans Over 70
Start by identifying where you will live and how often you will return to the United States.
Then consider your medical history, preferred hospitals, prescription needs, deductible, and budget.
Most importantly, check the policy’s entry-age and renewal rules before spending time comparing benefits.
A plan that looks attractive on paper may not be available to you because of its age limit or medical underwriting requirements.
Working with an independent insurance broker can make it easier to compare multiple providers instead of approaching each company separately.
Final Thoughts
International health insurance after 70 is possible, but your options can be more limited than they are for younger applicants.
Age limits, medical underwriting, pre-existing conditions, geographic coverage, U.S. coverage, deductibles, and renewal provisions all deserve attention before you choose a policy.
Medicare also needs to be considered separately because it generally provides limited coverage outside the United States.
If you’re over 70 and planning to retire or live overseas, start researching your insurance options before you move. Expat Global Medical can help you compare available international health insurance plans based on your age, destination, medical history, and coverage needs.
Request a free, no-obligation international health insurance quote and see what options may be available for your situation.